Sales are up this week. Good news—but what should you do next?
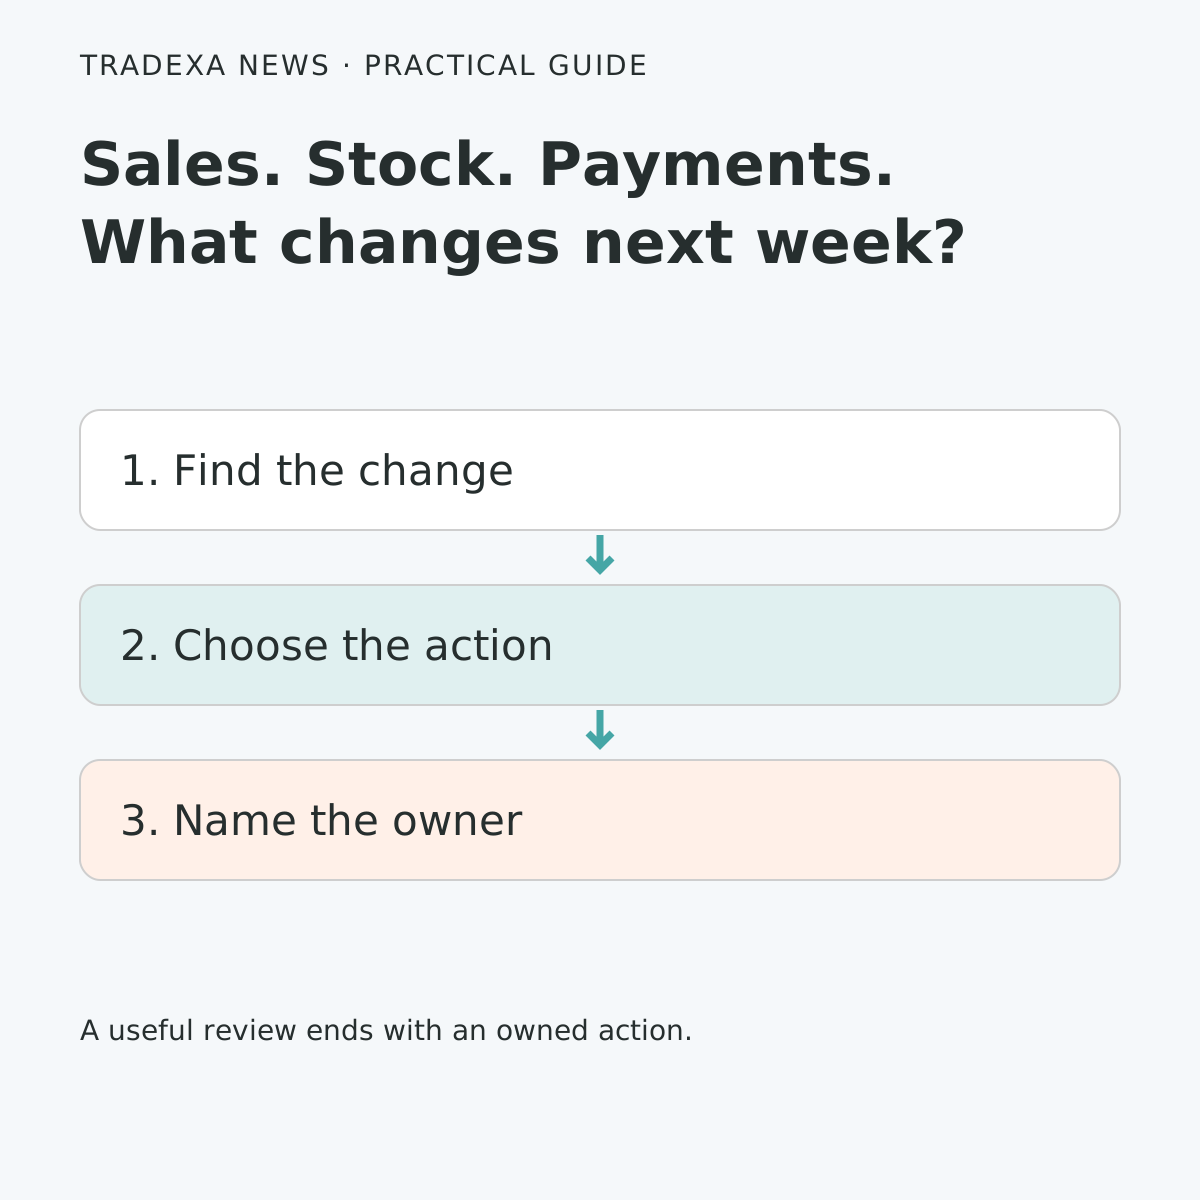
Before approving another purchase or a larger sales push, look at what sold, what is still on the shelf and what customers still owe. A useful weekly review connects those three questions and ends with a few owned actions. It should not leave the team with a larger report pack and the same uncertainty.
Use one period, then keep the measures distinct
Choose a weekly cut-off and a comparable previous period. Agree whether sales means orders received, invoices raised or retained sales after returns, and use that definition consistently. Note timing differences when a report has not caught up with the transaction cut-off.
Stock and customer outstanding are balances at a point in time. Sales is activity over a period. Put them beside each other, but do not add all three into a “business value” total: the same sale may already be represented in customer outstanding.
HyperInventory provides sales, purchase, payment and order reports, stock by branch and warehouse, stock ageing, and customer outstanding and aged receivables. Use the supported views relevant to your company and access permissions. This review method does not require or imply that every measure appears on one instantly refreshed screen.
Follow a finding across the business
Suppose one product sells 60 units a week and you hold 180 saleable, uncommitted units. At that unchanged rate, you have roughly three weeks of stock. A supplier offering a discount is not yet a reason to increase the purchase: check replenishment timing and existing commitments first.
Now suppose customer outstanding has risen from ₹8 lakh to ₹11 lakh. The ₹3 lakh increase is not automatically overdue or a loss. Finance needs to separate invoices still within terms from overdue invoices, disputed amounts and payments received but not yet matched.
The useful connection is the next decision. If you are considering more stock, ask which existing obligations need cash, what purchase is really required and which customer balances need action. A growing sales number can coexist with pressure on cash.
For detailed action on old stock or customer balances, use the stock-buying guide and customer-credit guide. This weekly review brings the findings together without repeating those investigations.
Make the review shorter by making the actions clearer
Begin the next meeting with the previous actions. Did the buyer check the lead time? Did finance resolve the disputed invoice? Did operations correct the stock discrepancy? If the answer is no, discuss the blocker rather than reopening every report.
Select a small number of material findings. A report can contain hundreds of products; the meeting needs decisions that change purchasing, fulfilment, collections or the next sales effort.
Suppose four people shorten a weekly meeting from 60 to 40 minutes because findings arrive with an owner and proposed action. Across 48 meetings, that releases 64 person-hours: four people × 20 minutes × 48 ÷ 60. It is capacity for other work, not a payroll saving. The product supplies relevant information; a disciplined review process makes the shorter meeting possible.
Copy this finding-to-action record
- Review cut-off and comparison period: record the dates and sales definition.
- Finding: name the product, branch or customer and the observed change.
- Evidence: identify the report, transaction or balance behind it; note refresh or matching gaps.
- Decision: purchase, investigate, collect, transfer, promote or wait; say why.
- Owner and due date: one person responsible for the next step.
- Expected sign of progress: the observable change you will check at the next review.
- Follow-up result: completed, blocked or revised, with the reason.
A weekly review earns its place when information changes a decision. Connected sales, stock and payment records can help you choose where the team’s next hour and the business’s next rupee should go—while keeping the final judgement with the people running the business.
Example note: Quantities, balances and meeting times are illustrative. The stock-cover calculation assumes the same sales rate and excludes future demand changes; substitute your actual inputs.