Orders are up, the sales team is pleased, and the supplier payment is due. Yet the bank balance feels tighter than last month.
If customers are buying on credit, more invoiced sales can mean more money waiting to be collected. The business may be growing and still have less room to place the next order. Start by separating sales, outstanding invoices and amounts already overdue.
Which invoices actually need action?
An invoice that is not yet due is outstanding but not overdue. An invoice past its agreed due date needs a different conversation. Treating them alike can waste follow-up effort and strain a good customer relationship.
Group the balance by customer and due date. Then examine disputes, missing documents, unallocated payments and genuine late payment. Each needs a different next step.
For example, a customer who has paid but whose receipt is not matched does not need another payment demand. They need the records corrected.
How much buying room is waiting in collections?
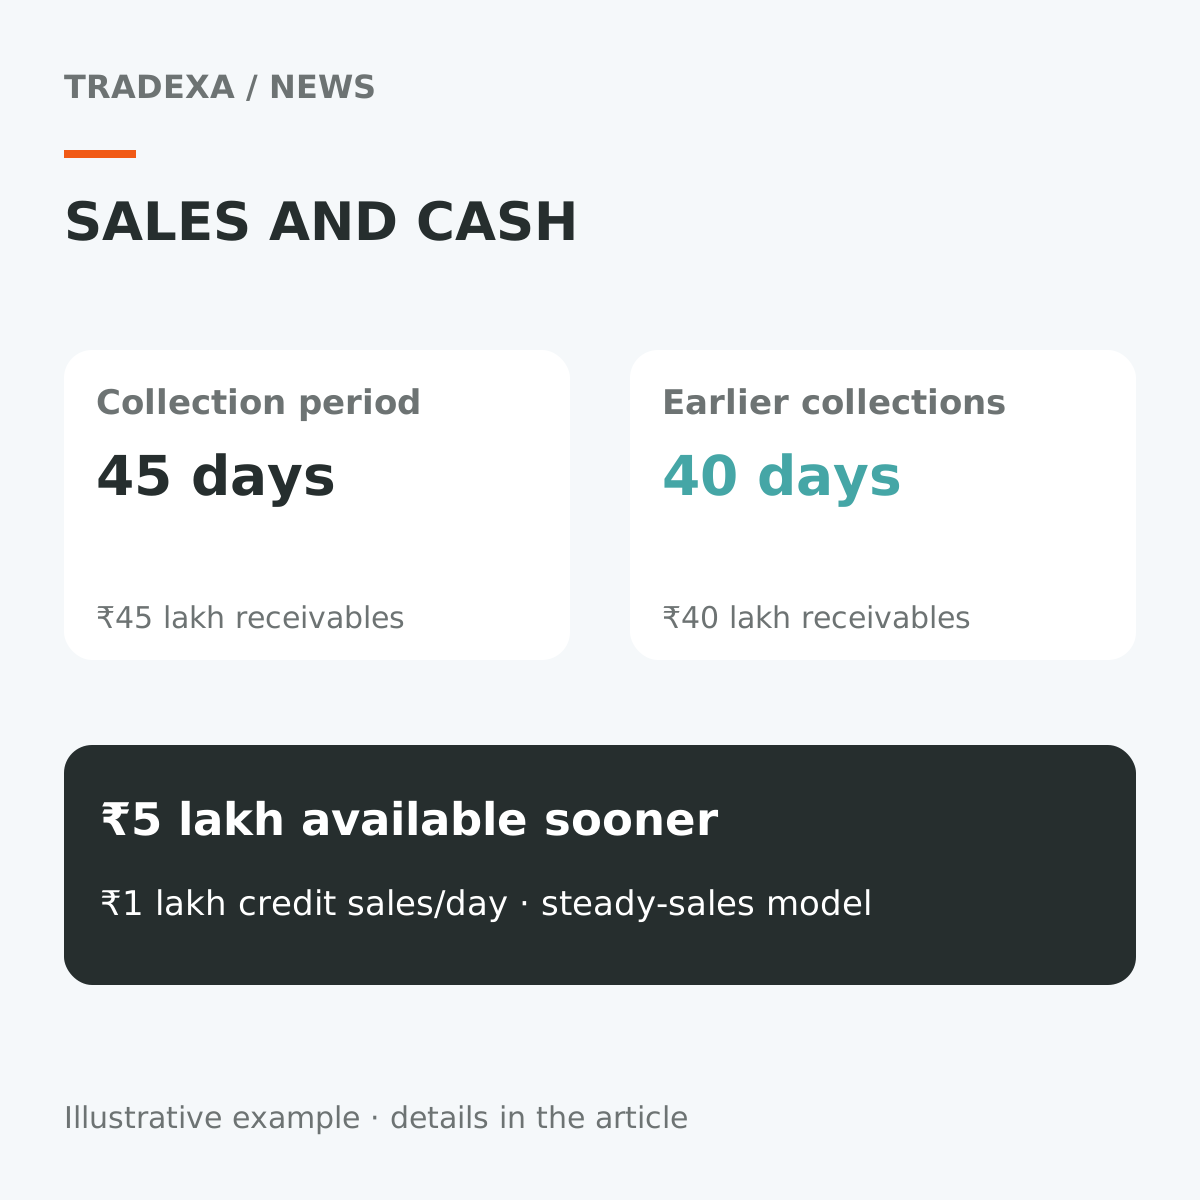
Take an illustrative business making ₹30 lakh of credit sales in a 30-day month: roughly ₹1 lakh a day. If collections currently average 45 days, a simple steady-sales model implies ₹45 lakh tied up in receivables.
Reducing that average to 40 days could bring the balance to ₹40 lakh, releasing ₹5 lakh once the lower collection period is sustained. This assumes steady sales and broadly similar payment patterns; it is not a forecast for a seasonal business.
The mechanism matters. In this scenario, sending missing documents promptly, matching receipts and acting on overdue invoices would need to bring collections forward by those five days. Seeing a report alone does not do that.
₹5 lakh collected sooner is not ₹5 lakh extra profit. It is money available earlier for supplier payments or other business needs. At an illustrative 12% annual financing rate, a sustained ₹5 lakh lower borrowing requirement would reduce financing cost by ₹60,000 a year. Actual borrowing terms and timing determine whether that saving exists.
Will the next order deepen the problem?
Before extending more credit, look at the customer's existing balance, due invoices and unresolved disputes. A large order is not necessarily attractive if it increases an already difficult exposure.
HyperInventory supports credit limits in configured order and invoice workflows, along with aged-receivables visibility. Confirm the exact enforcement points in your setup; do not assume every sales channel applies an identical block.
A limit is not a replacement for a commercial decision. Someone still needs responsibility for exceptions, terms and collection follow-up.
Make follow-up easier to act on
Give the person contacting a customer a usable record: invoice, amount, due date, related documents and any payment already received. Agree a next date or action rather than repeatedly sending the same reminder.
Tradexa's reporting and supported accounting connections can help bring the operational and finance records into a clearer workflow. Your finance team still needs to reconcile them and decide how balances should be treated.
The growth benefit is not harsher credit control. It is choosing which business you can fund, collecting with less confusion and keeping successful sales from preventing the next worthwhile purchase.